Analysis · Transport & Logistics
Baltic Airports: Summer Records Meet Expectations of a Winter Slowdown
Passenger trends diverge across the Baltics as airlines reshape winter routes, including a marked reduction in direct services between Lithuania and Germany.
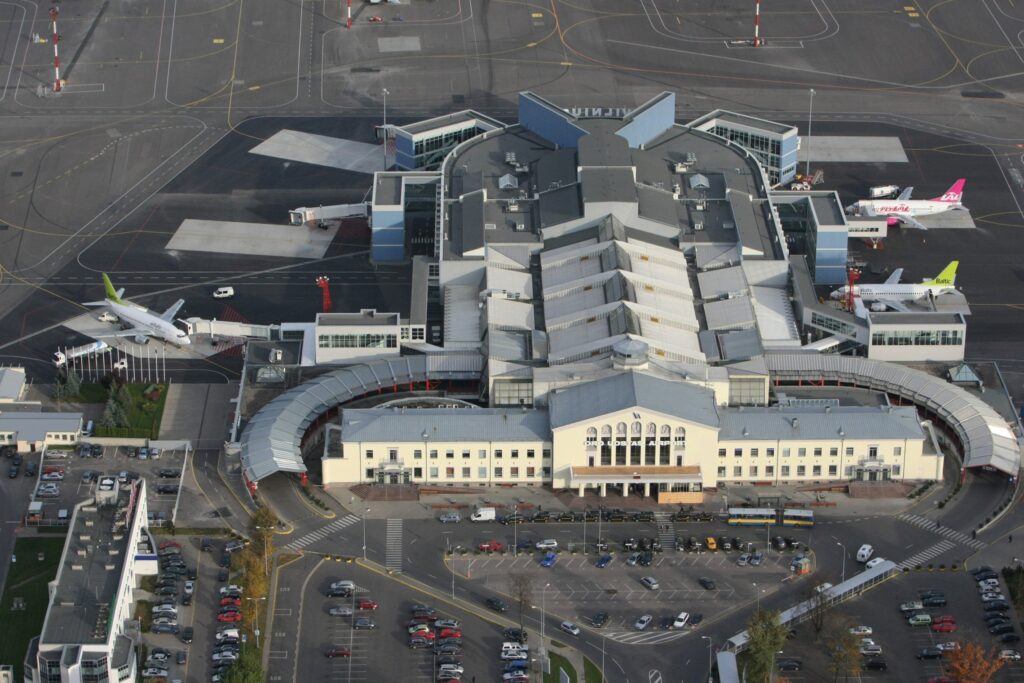
The Baltic aviation market is entering the 2026/27 winter season with contrasting passenger trends and significant changes in airline strategies. Riga remains the region’s largest individual airport, but passenger traffic has declined. Lithuania’s airport network continues to expand, driven by Vilnius, while Tallinn has set another monthly record.
Yet passenger numbers tell only part of the story. Airlines are redistributing capacity across the region, expanding some connections while withdrawing others. The changes are particularly visible in low-cost services and routes linking the Baltic states with Germany.
DATA CARD | Baltic Passenger Traffic
January–October 2026
| Airport / network | Passengers | Year on year |
|---|---|---|
| Riga | 5.97 million | −1% |
| Lithuania · 3 airports | Over 6.6 million | +8.3% |
| Tallinn | 3.27 million | +11% |
Lithuania includes Vilnius, Kaunas and Palanga. Riga and Tallinn figures refer to individual airports.
October largely marked the end of the summer aviation season, with winter schedules taking effect on 25 October. Riga handled an estimated 650,000 passengers, about 4% fewer than a year earlier. Vilnius recorded 9.2% annual growth, while Tallinn registered its busiest October on record, with passenger numbers up 7.5%.
The winter programmes show how differently airlines are responding to these market conditions.
Riga: Airlines Redistribute Capacity as Passenger Traffic Declines
Riga remains the Baltic region’s main passenger hub, but its traffic has weakened despite a modest increase in aircraft movements.
The balance between its two largest airlines is also changing. airBaltic has strengthened its relative position, while Ryanair’s share of passenger traffic has declined compared with its full-year 2025 level.
DATA CARD | RIX Riga Airport
Passenger market shares · January–October 2026
| Airline | Market share |
|---|---|
| airBaltic | 59% |
| Ryanair | 19% |
For reference, their respective full-year 2025 shares were 57.2% and 22.8%. Reporting periods differ.
Winter 2026/27
- 63 scheduled destinations in 30 countries
- 11 scheduled airlines
- Ryanair: +6% planned seat capacity
The winter schedule reflects contrasting decisions by the two carriers.
airBaltic has removed 12 destinations from its winter programme, including Bucharest, Sofia, Budapest and Oulu, and reduced frequencies on several other routes. The airline cites seasonal demand, changing market conditions and higher operating costs. It is nevertheless introducing winter services to Kuusamo in Finland and Turin in Italy.
Ryanair is moving in the opposite direction. The Irish low-cost carrier is increasing frequencies to Dublin, Milan, Barcelona, Málaga and several other destinations. Its Málaga service, for example, rises from three to five flights per week compared with last winter.
LOT Polish Airlines is also strengthening its Warsaw connection, increasing frequencies from 17 to 20 weekly services, while Norwegian is retaining its Bergen and Gothenburg routes.
Riga is therefore entering winter with weaker passenger traffic but an expanding offer from selected carriers. The changes could gradually alter the balance of competition at an airport historically dominated by airBaltic.
Lithuania: Vilnius Drives Growth, While Regional Airports Lose Passengers
Lithuanian Airports (LTOU), which operates Vilnius, Kaunas and Palanga airports, completed a record seven-month summer aviation season. However, the October results reveal an important difference within the national network.
Vilnius continued to grow strongly, while Kaunas and Palanga together handled fewer passengers than a year earlier.
DATA CARD | Lithuanian Airports
October 2026
| Airport / network | Passengers | Year on year |
|---|---|---|
| Vilnius | 554,000 | +9.2% |
| Kaunas + Palanga | ≈184,000 | ≈−7.5% |
| Lithuania · total | 738,000 | +4.5% |
Kaunas and Palanga are shown together because the October release provides their combined total by subtraction. Changes are approximate.
Winter 2026/27 · Scheduled routes
| Airport | Routes |
|---|---|
| Vilnius | 48 |
| Kaunas | 15 |
| Palanga | 6 |
69 scheduled routes across the three airports; 77 including charter routes.
The winter network offers opportunities for expansion despite the uneven October results. Vilnius will have direct connections to 20 European capitals, two more than last winter. Frequencies are increasing to major hubs including Warsaw, Helsinki, Copenhagen and Frankfurt, while a new Geneva service is scheduled to begin in January.
Kaunas is strengthening connections to Edinburgh, London, Liverpool, Alicante and Stockholm. Palanga is increasing frequencies to Copenhagen, supporting connections between western Lithuania and Scandinavia.
However, the German market presents a more difficult picture.
Lithuania–Germany: Fewer Flights and a Contractual Dispute
The winter schedules reflect a substantial reduction in the number of weekly services between Lithuania and Germany.
DATA CARD | Lithuania–Germany Connections
Published seasonal flight programmes
| Indicator | Weekly flights |
|---|---|
| Summer programme cited by LTOU | 44 |
| Winter 2026/27 | 28 |
| Difference | −36% |
Seasonal comparison published by Lithuanian Airports, not a year-on-year change.
These reductions are accompanied by concrete decisions from two airlines.
Ryanair has withdrawn its Vilnius–Berlin service as part of wider reductions at Berlin Airport. Wizz Air has introduced its own Berlin connection, while Lufthansa is increasing Frankfurt frequencies. Nevertheless, the changes reduce the range of low-cost options available on German routes.
The more serious dispute concerns airBaltic’s decision to discontinue direct flights between Vilnius and Düsseldorf from 23 November.
The route was launched in October 2024 under a commercial risk-sharing agreement with Lithuanian Airports. According to airBaltic, passenger demand and revenue fell short of its business-plan expectations, while operating costs, particularly fuel, exceeded initial forecasts. The airline considers continued operation commercially unviable.
Lithuanian Airports takes a different position. It considers Düsseldorf strategically important and believes the route retains commercial potential. The airport operator intends to challenge airBaltic’s unilateral termination of the agreement and seek recovery of funds invested in developing the service if its contractual demands are not met.
The dispute has emerged during airBaltic’s financial restructuring under Chapter 11 of the US Bankruptcy Code, initiated in September 2026. The process allows the airline to reorganise its obligations while continuing operations, but has also created uncertainty around existing commercial agreements.
LTOU intends to defend its position in the US proceedings and, if necessary, pursue further legal action in Lithuania. It has also begun negotiations with alternative airlines to restore the Düsseldorf connection.
The route carried approximately 37,000 passengers since its launch, with two weekly flights.
The case extends beyond a single destination. It raises questions about the durability of risk-sharing agreements used to develop strategically important air connections, particularly when an airline undergoes financial restructuring.
Lithuania is thus entering winter with a growing overall network but fewer flights to Germany and an unresolved dispute over the future of a direct international connection.
Tallinn: Record Passenger Growth, but a More Cautious Winter
Tallinn Airport ended the summer aviation season with another record. October passenger traffic reached nearly 375,000, up 7.5% year on year, supported by the expansion of Wizz Air.
The Hungarian low-cost carrier has rapidly strengthened its position in Tallinn, although airBaltic remains the airport’s largest airline.
DATA CARD | Tallinn Airport
Passenger market · October 2026
| Airline | Market share |
|---|---|
| airBaltic | 23% |
| Wizz Air | 15% |
Winter 2026/27
| Indicator | Value |
|---|---|
| Direct destinations, including charters | 41 |
| Scheduled airlines | 15 |
| Expected capacity change YoY | −9% |
Market shares refer to October only. Winter capacity is the airport’s forecast.
Despite record passenger traffic, Tallinn expects overall winter flight capacity to be approximately 9% lower than in the previous winter season, reflecting airline network adjustments and higher fuel prices.
Wizz Air’s expanded network includes Budapest, Kraków, Rome, Venice and other European destinations, strengthening Tallinn’s position in the city-break market.
airBaltic maintains direct services to major European cities including Amsterdam, Brussels, Geneva, Munich and Paris. Ryanair continues to serve selected destinations but has withdrawn the Berlin connection.
The airport’s recent growth therefore contrasts with a more restrained winter outlook. Expansion by Wizz Air is helping diversify the market, but reductions by other carriers demonstrate that strong passenger demand does not necessarily translate into more capacity across the entire network.
A Changing Competitive Balance Across the Baltics
The differences between the three markets are especially visible in Ryanair’s winter plans.
DATA CARD | Ryanair Winter 2026/27
Announced seat capacity changes
| Market | Year on year |
|---|---|
| Riga | +6% |
| Lithuania and Estonia combined | −25% |
Ryanair’s announced winter seat capacity, not total airport passenger traffic.
Ryanair attributes its regional capacity decisions partly to differences in airport access costs. Lithuanian Airports disputes the carrier’s characterisation of rising charges in Vilnius, noting that the tariffs introduced in 2023 have remained unchanged and that their legality was upheld by the courts.
The contrasting positions illustrate the commercial negotiations behind airline route decisions, while airBaltic’s restructuring adds another source of uncertainty.
The Baltic aviation market is entering winter with three different developments: Riga is experiencing weaker passenger traffic but additional capacity from selected competitors; Lithuania’s growth is concentrated in Vilnius while important German connections are being reduced; and Tallinn faces a smaller winter capacity programme despite record passenger numbers.
For businesses and passengers, the significance of these changes extends beyond airport traffic statistics. The availability of direct connections, flight frequencies and airline choice will determine how effectively the region remains connected to its European markets.
